If money is meant to flow, why would you keep some of it to accumulate? Why dont you just spend it?
There are several reasons why you should keep back or save some of it.
- 1. Money Flow Interruption – You are probably dependent on some activity, probably work, for your money inflow. If you are unable to work for some reason, then the money will stop.
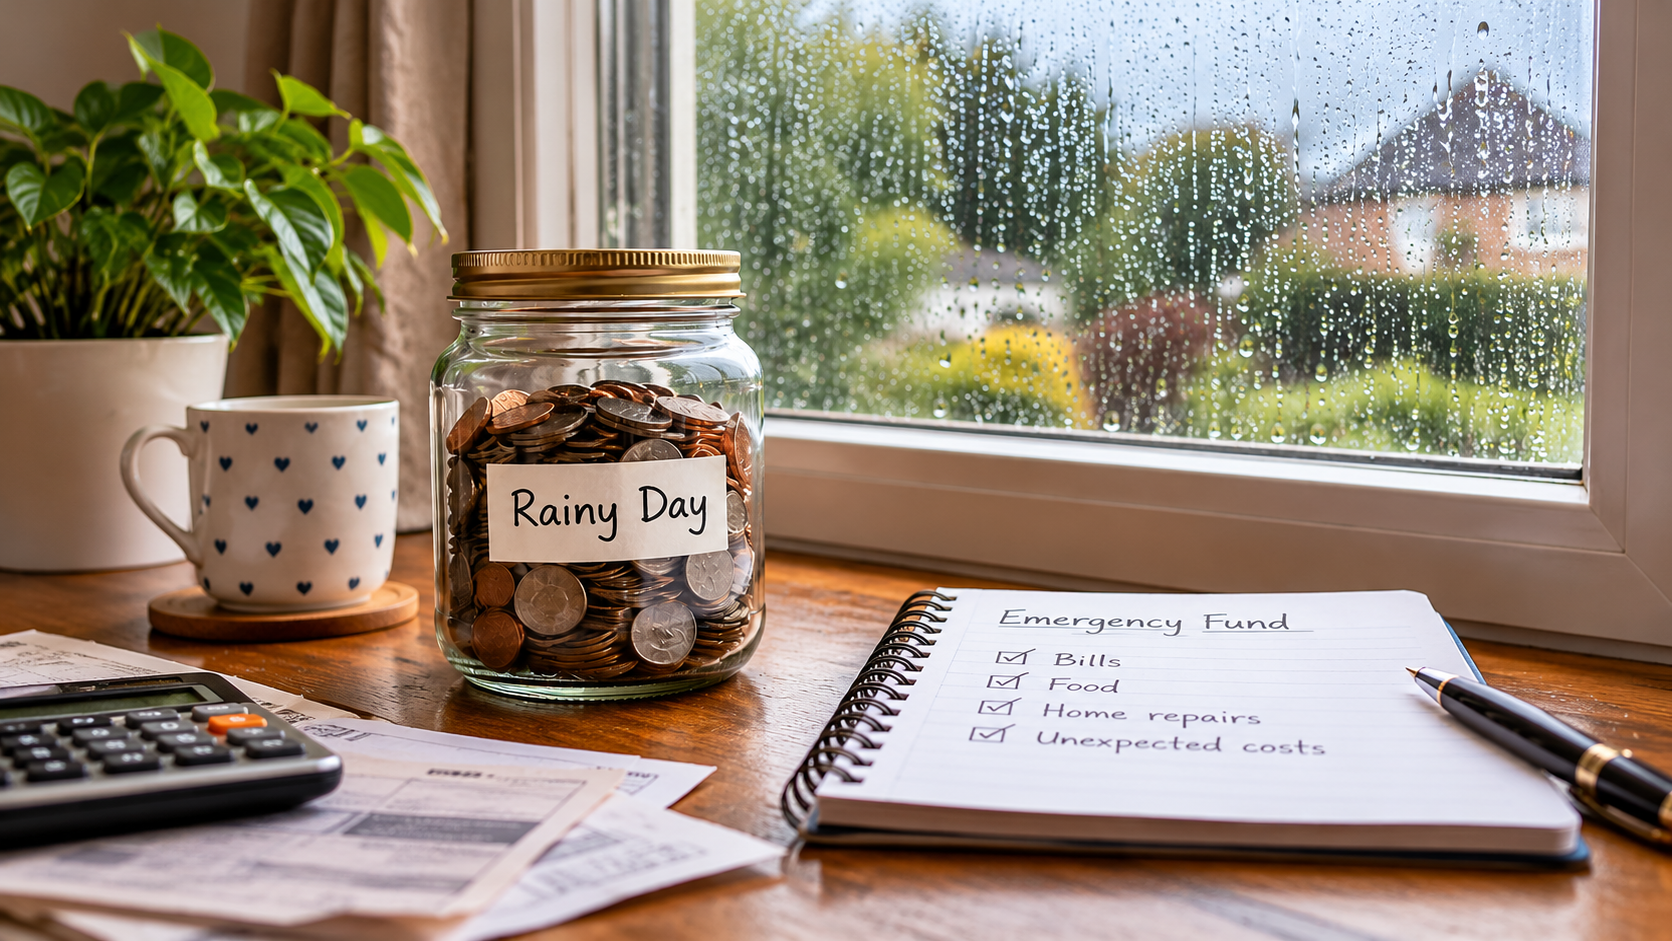
This may be due to illness or unfavourable conditions. For example, in the past, when agricultural workers were paid by the day, when it was raining and the ground was wet, they could not work and so did not get paid. If they did not have money saved, then they could not buy food. Hence today we still hear the expression ‘Saving For a Rainy Day’. - 2. Unexpected Bills – There are always expenses cropping up unexpectedly, and they often have to be paid immediately. There needs to be a pot of saved money available to draw on. Otherwise, there won’t be money to pay for immediate necessities.
- 3. Variable bills – Sometimes you get bills that vary from month to month, and therefore you don’t know exactly how much you will need. A prime example is utility bills – such as electricity, gas, water and phone bills. These vary through the year according to how much you use. Utility companies are notorious for keeping customers’ money and keeping them in the dark. Here, there are several tools available from your Bank which can help and give you more peace of Mind.
Royal Bank of Scotland offer several ‘Pots’ where you can decide to have a certain amount of money put aside for certain bills in advance and then pay them from the Pot when they become due. Other Banks offer similar services, but you will have to ask to find out how to set them up.
Borrowing – Before we go on, can we talk briefly about borrowing? It has never been easier to borrow money to pay your immediate difficult bills, and many organisations will be glad to lend it to you. Do so.
However, everything comes at a price! You will pay for that loan for every full month until you repay it. It may surprise you to know the organisation does not want you to pay them back. It would rather have the monthly interest payment from you.
It is very easy to get into debt and very hard to get out of it.
- 4. Old Age Support The fourth reason for accumulating some of the money that flows through your hands is that a time will come when you can’t work to generate money to support yourself
In the old days in Western countries, and still elsewhere, people had lots of children to ensure someone would be around to feed and shelter them when they became old and unable to work.
Pensions – In the West, this has gradually been replaced by a system that provides replacement income until you die.
State Pensions – The more economically developed countries started pension schemes run by the government as long as 100 years ago. These were run by the State but contributed to by the individuals. These have been run well or badly by different governments in different countries. As a result, it is better not to rely exclusively on the State in your country for your income in old age. It may be enough to keep you alive, but with a very poor quality of life.
Private Pensions – With these, you pay a regular contribution, and the Pension Company invests the money on your behalf. Because they employ investment experts, the growth rate is better than you could achieve. The downside is that the pension company takes its costs and profits out of your money before you get it. You need to take advice from an Independent Financial Advisor (IFA) to make sure you get a good deal.
Independent Savings Plans. – However good your provision is for your old age, it is desirable to have your own savings pot building up in the background to be available for a major life change if one occurs. This could be the end of a marriage, a move to another area, or starting a business of your own.
There are two enemies, however, to your savings pot holding its value. These are taxation and inflation. In the UK, we have an Independent Savings Plan, known as an ISA, which escapes the effects of both taxation and inflation.
We have an article and interview below which explains how this works and how you can get on board. I am trusting that a similar scheme exists in other countries, but you will have to enquire.
Additional Resources
Second pillar of financial literacy – Insure
Midlife Money: The Importance of Financial Literacy